In brief
- A certificate of incorporation is not permission to trade. Before its first invoice a Kenyan company needs its KRA PIN, eTIMS onboarding, VAT registration where turnover will cross KES 5 million, the county single business permit, and whatever licence its own sector demands, and the gap between the certificate and that stack is where new businesses lose their first months.
- Compliance then becomes a calendar. The annual return goes to the Registrar within 28 days of the company’s incorporation anniversary under section 705 of the Companies Act, changes in beneficial ownership are lodged within 14 days, tax returns run on their own cycle, and the first hire triggers a payroll file of its own.
- The whole obligation fits on one page, and the businesses that keep that page never meet the penalties, the stalled tax compliance certificates or the strike-off list. The ones that reconstruct it at year three pay advisers to do what a diary would have done.
Full Article
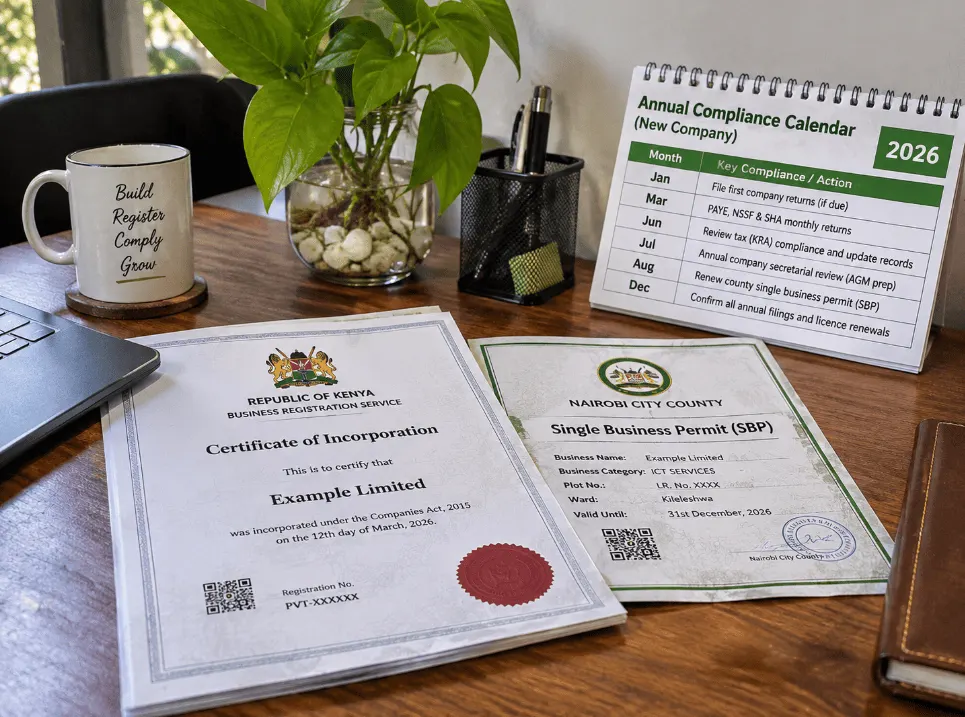
The certificate of incorporation arrives by e-mail and feels like the finish line, and for the Registrar it is. For everyone else it is the starting gun. The bank wants more than the certificate, the first customer wants a compliant invoice, the county wants its permit before the doors open, and the Kenya Revenue Authority wants the company inside its systems before any of it. This article sets out what a newly incorporated Kenyan company actually needs before it trades and the calendar it keeps afterwards, and it serves the local founder and the foreign-owned company alike. It continues from our article on how to register a company in Kenya as a foreigner and what it costs, and it is written for the reader holding a fresh certificate and a list they suspect is incomplete.
The tax file comes first
The company’s first stop is the KRA. The company PIN opens the tax file and everything else depends on it, the bank account, the permits, the contracts with anyone who checks compliance. Onboarding to eTIMS, the electronic invoicing system, has been mandatory for businesses of every size since September 2023, and the pressure behind it is practical rather than polite, because only an eTIMS invoice is deductible in the hands of your customer, which means serious customers will not transact without one, and since late 2025 a company cannot obtain a tax compliance certificate without it. VAT registration is obligatory once taxable turnover reaches or will reach KES 5 million in a year, and voluntary registration earlier sometimes serves businesses whose customers expect VAT invoices. The sequence is a morning’s work when done at incorporation and a month’s untangling when done after the first deal is waiting.
The county, and the sector
Trading from premises needs the county’s single business permit, renewed annually, with the fee set by each county’s finance act and scaled to the size and type of the business, so the figure is confirmed against the county’s current schedule rather than folklore. That is the universal licence. On top of it sits the sector stack, and the stack is the part that needs mapping before the lease is signed rather than after. A restaurant or resort collects health certificates, fire clearance, liquor licensing and tourism regulatory licensing. A manufacturer meets environmental approvals before ground breaks. A transporter, a school, a clinic, a money-handling business, each has a regulator with a licence and a timetable of its own. The discipline we press on clients is one page listing every licence the business model touches, with its issuer, fee, processing time and renewal date, prepared before trading begins, because the cost of the page is an hour and the cost of its absence is an opening delayed by the one approval nobody had started.
The first hire changes the file
Employment brings its own registrations, and they arrive together. The employer registers for PAYE and deducts it monthly, enrols with the National Social Security Fund and the Social Health Insurance Fund, remits the affordable housing levy, and registers with the National Industrial Training Authority, with everything now flowing through a single payroll return by the ninth of the following month. The current rates and bands are tabled in our article on statutory deductions in Kenya, and the point for a new company is simpler than the rates, which is that payroll compliance starts with the first employee, including a founder who pays themselves a salary, and backdating registrations after a year of informal payments is expensive in penalties and worse in audits.
The standing calendar
Then comes the rhythm. The annual return goes to the Registrar within 28 days of every anniversary of incorporation under section 705 of the Companies Act, 2015, confirming the company’s particulars, and the company that ignores it accumulates offences and eventually meets the strike-off list. The register of beneficial owners must be kept current, with changes lodged with the Registrar within 14 days, on pain of administrative penalties that grow by the day. Corporation tax returns and instalment taxes run on the KRA’s cycle, the county permit renews each January, the sector licences renew on their own dates, and a company holding personal data registers with the Office of the Data Protection Commissioner and renews that certificate too, the subject of our article on data protection registration in Kenya. Written out, it is a dozen dates. Kept in one diary with sixty-day reminders, it is a quiet afternoon per quarter. Reconstructed under pressure, during a financing, a tender or a dispute, it is the most expensive housekeeping a company ever buys.
What happens next
For a company incorporated this quarter, the useful exercise is the one-page compliance map, every registration, licence and renewal the business model touches, dated and owned. We prepare it as part of every incorporation instruction and audit it for companies already trading, and the difference it makes shows up precisely when the company cannot afford surprises, at the bank, the tender and the due diligence. To have a new company’s licensing stack mapped, a compliance file audited or a stalled registration rescued, the place to start is a conversation.
Frequently asked questions
What does a company need before it can start trading in Kenya?
Its KRA PIN, eTIMS onboarding, VAT registration where turnover will reach KES 5 million, the county single business permit for its premises, and any licence its sector requires, health, liquor, tourism, environmental or regulatory. The certificate of incorporation alone does not authorise trading from premises or compliant invoicing.
Is eTIMS mandatory for a small or new company?
Yes. Onboarding has been mandatory for businesses of all sizes since September 2023, with simplified options for the smallest traders. Only eTIMS invoices are tax deductible for your customers, and a company now needs eTIMS compliance to obtain a tax compliance certificate, so serious counterparties will expect it from the first invoice.
When are annual returns due in Kenya?
Within 28 days of each anniversary of the company’s incorporation, filed with the Registrar under section 705 of the Companies Act, 2015. Persistent default is an offence for the company and its officers and ultimately risks the company being struck off the register.
What is the deadline for beneficial ownership changes?
Changes to a company’s beneficial ownership must be lodged with the Registrar within 14 days, and the register must be kept accurate in the meantime. Late lodging attracts administrative penalties that accrue daily, which makes beneficial ownership a diary item rather than a one-off filing.
What does a single business permit cost?
It varies by county and by the size and type of the business, because each county sets its fees in its own finance act and reviews them yearly. The permit renews annually, and the reliable approach is to confirm the current schedule with the county where the premises sit before budgeting, rather than relying on last year’s figure.
Peter Maina is a Partner of Peter Maina & Company Advocates. This article states the law as at 17 November 2026. It is general information, not legal advice. To map a new company’s licensing stack, audit a compliance file or rescue a stalled registration, reach out on e-mail peter@pmlaw.co.ke or WhatsApp +254 714 644 080.
Leave a Reply